Coinbase vs Gemini: Fees, Custody, Staking and Taxes Compared
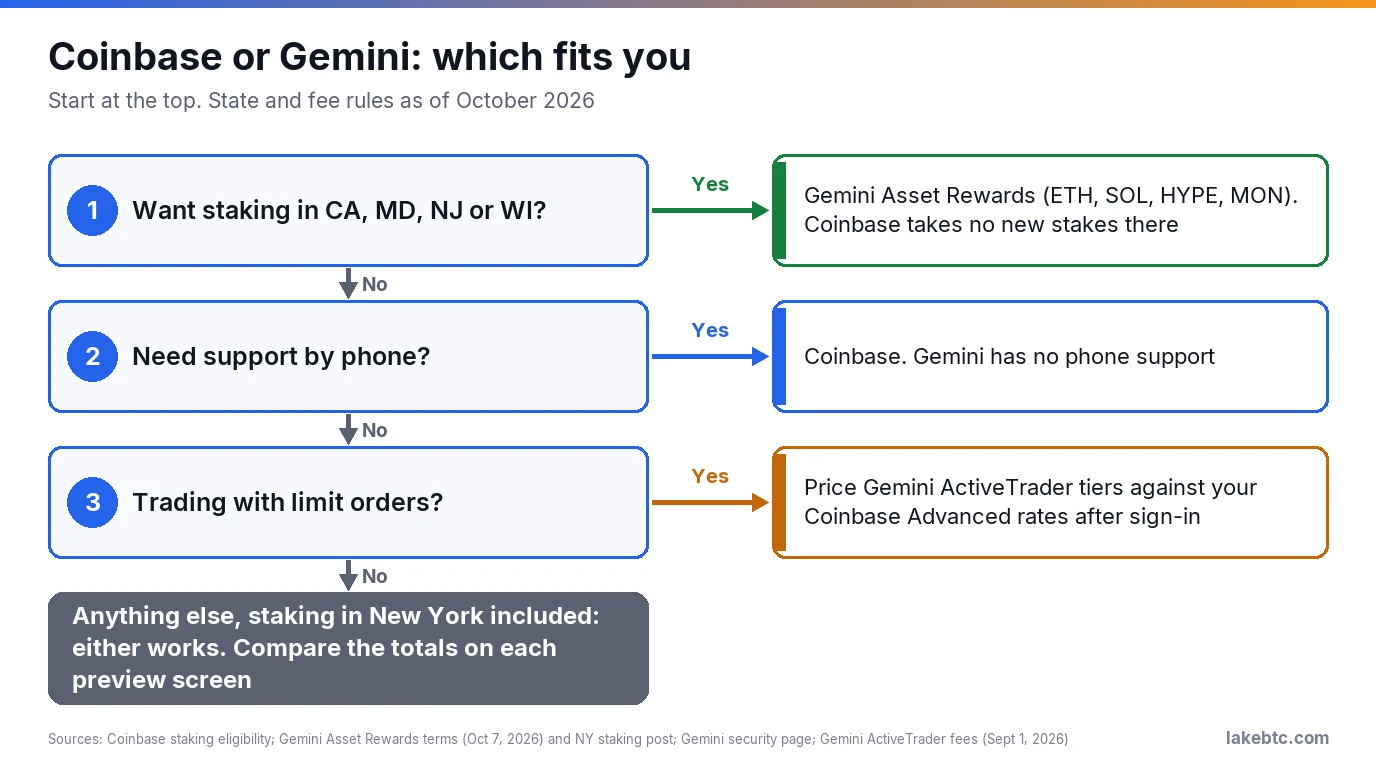
Both are custodians. Coinbase has phone support. Gemini publishes its ActiveTrader fees and pays staking rewards in CA, MD, NJ and WI, where Coinbase takes no new stakes.
Start with what’s the same. Both companies can keep your coins in shared wallets they control, and both contracts say those coins stay yours. Both carry crime insurance that covers only part of what they hold, and FDIC insurance doesn’t cover your crypto on either. Your dollars are different. The part each keeps as bank cash sits in accounts set up for pass-through deposit insurance up to $250,000 (FDIC, or NCUSIF at Coinbase’s credit unions), though both may also hold customer dollars in Treasuries or money market funds.
So the choice comes down to your order type, staking, your state and how you reach support. The numbers below are the ones each company publishes, checked in October 2026.
Before you pick one
- 🟢 Both treat the crypto in your account as yours, not company property, under their user agreements.
- 🟡 A simple limit order in the Coinbase app adds a 1% execution fee on top of any Coinbase fee.
- 🟡 Coinbase takes no new stakes in CA, MD, NJ or WI. In New York, Gemini Asset Rewards is closed, but Gemini Staking takes ETH and SOL.
- 🔴 Gemini has no phone support and says it won’t cold-call you about support or your account, so treat an unexpected call from “Gemini support” as a scam. Coinbase staff never ask you to move funds to a new address.
In this article
- Which one fits what you’re about to do
- What you’ll pay on each screen
- Who holds your crypto and your cash
- Staking: the cut each takes and where it’s off
- Security and legal record
- Moving crypto between Coinbase and Gemini
- Support, and the scam that copies it
- Tax forms you’ll get from each
- Frequently Asked Questions
- What to do next
Which one fits what you’re about to do
Pick by the thing you’ll do most with the account.
You want staking rewards in California, Maryland, New Jersey or Wisconsin. Coinbase takes no new stakes from these four states. Gemini’s Asset Rewards pays rewards on ETH, SOL, HYPE and MON there, though California and New Jersey residents have to switch it on first.
You want staking rewards in New York. Both can do it, through different products. Coinbase staking is open to New York residents. Gemini’s Asset Rewards isn’t, but Gemini Staking, its separate product with unbonding waits, has taken ETH and SOL from New York customers since February 10, 2026.
You want to reach a person by phone. Coinbase runs phone support. Gemini has no phone support and answers by email.
You trade with limit orders. Gemini posts every ActiveTrader tier publicly, so you can price a trade before you sign up. Coinbase shows your Advanced rates only after you sign in, and a limit order on its simple screen costs extra.
You buy now and then and hold. Either one works. You pay a spread plus a fee that depends partly on your payment method, so compare each app’s preview for the same amount and payment method.
What you’ll pay on each screen
Neither company publishes a fixed rate for its simple Buy button. Coinbase builds a spread into the quoted price and adds a fee, and you’ll see both on the order preview screen. Gemini’s app works the same way. So the fair comparison is per order type.
| What you’re doing | Coinbase | Gemini |
|---|---|---|
| Simple buy or sell in the app | Spread in the price plus a Coinbase fee, both on the order preview | Spread in the price plus a fee, both on the trade review screen |
| Limit order on the simple screen | 1% limit order execution fee, plus possibly a 1.875% Coinbase fee, depending on payment method | No separate limit order fee on its app fee page; on ActiveTrader, a limit order that rests on the book pays the maker rate |
| Order book, lowest tier | Coinbase Advanced: no spread; your maker and taker rates show after you sign in | ActiveTrader: 0.600% maker, 1.200% taker |
| Order book, next tier | Shown after sign-in | 0.400% maker, 0.800% taker from $10K of 30-day volume or a $1M balance |
| Bank transfer (ACH) | Fee, if any, shown before you confirm | Free in and out |
| Wire | $10 in, $25 out | Free in, $25 out |
| Debit card or PayPal | Fee shown before you confirm | Debit card 3.49% of the purchase; PayPal 2.50% of the deposit |
| Sending crypto out | Coinbase’s estimate of the network fee; free to another Coinbase user | Dynamic fee that tracks the network fee |
| Anything else | On the preview screen | On the review screen |
Put a $1,000 trade through those numbers. On Gemini’s ActiveTrader schedule of September 1, 2026, it costs $12 as a taker or $6 as a maker. A $1,000 limit order on Coinbase’s simple screen carries a $10 execution fee, and the 1.875% Coinbase fee, if your payment method draws it, adds $18.75.
Both order books set your tier the cheaper way: ActiveTrader by 30-day volume or total balance, Coinbase Advanced by volume or USDC balance. Coinbase’s fee help page sends you to sign in for the actual rates.
There’s also a subscription. Coinbase One starts at $4.99 a month, and its Basic plan lists zero trading fees up to $500 a month. A spread still applies, the limit order execution fee isn’t waived, and the zero fees don’t cover Coinbase Advanced.
Who holds your crypto and your cash
If either company fails or gets hacked, start with two things: what the contract says your coins are, and how much insurance stands behind them.
Your Gemini account isn’t always with the New York trust company. Residents of Idaho, Louisiana, New York, Ohio and Texas are under the Gemini Trust Company agreement. Residents of every other state, DC and Puerto Rico are with Gemini Moonbase, LLC, a Delaware company headquartered in Florida and overseen by state regulators. On Coinbase, the US user agreement is with Coinbase, Inc.
| Question | Coinbase | Gemini |
|---|---|---|
| Who your contract is with | Coinbase, Inc. | Gemini Trust Company (ID, LA, NY, OH, TX) or Gemini Moonbase (other states, DC, PR) |
| What it says about your crypto | Title stays with you; held for customers, not Coinbase property, and outside the reach of its creditors | Not treated as Gemini’s general assets; you keep full title |
| Crypto insurance | Crime insurance on a portion of digital currency; no amount published | $25.0 million crime cover for the hot wallet, $100.0 million specie cover for cold storage |
| Not covered | Losses after your login details are stolen; NFTs | Losses after someone gets into your account, for crypto and for cash; crypto above the policy limits |
| Your US dollars | FDIC-insured banks or NCUSIF credit unions with pass-through up to $250,000, or Treasuries and money market funds | Cross River Bank and Customers Bank with pass-through up to $250,000, or Treasuries and money market funds; Moonbase may also use qualifying stablecoins |
| Anything else | FDIC, NCUSIF and SIPC don’t cover crypto | FDIC and SIPC don’t cover crypto |
Insurance is thin on both. Gemini’s 2025 annual report lists two policies totaling $125 million. Its June 2026 quarterly report puts assets on the platform at $8.4 billion, so that cover comes to about 1.5% of them.
Coinbase doesn’t publish its figure. Its annual report says it aims to keep no more than 2% of custodied assets in hot wallets and always holds more corporate assets than those wallets contain, but calls total customer assets “substantially more than our corporate assets and available insurance.”
The contract wording matters more than the insurance. If either company went bankrupt, those clauses are what you’d rely on to keep your coins out of its estate. Courts haven’t yet ruled on that treatment for custodied crypto, a caveat in Coinbase’s own filing. Gemini’s filing makes the same argument: it believes the crypto it holds for you is your property, out of reach of its general creditors.
Staking: the cut each takes and where it’s off
Both keep a share of what the network pays, up to 35% on the main assets. The bigger differences are state rules and how you join. Gemini runs two programs here. Asset Rewards is the one most accounts land in, and the table follows it. Gemini Staking is a separate product with an unbonding wait.
| Staking | Coinbase | Gemini Asset Rewards |
|---|---|---|
| Commission | 35% on ADA, ATOM, AVAX, DOT, ETH, MATIC, SOL and XTZ; Coinbase One tiers pay 31.75%, 28.5% or 25.25% on six | Up to 35% on ETH, SOL, HYPE and MON |
| California, New Jersey | No new staking | Available if you opt in |
| Maryland, Wisconsin | No new staking | On automatically; you can opt out |
| Illinois, Texas, Washington, Massachusetts | Available | Available if you opt in |
| New York | Available | Not available; Gemini Staking takes ETH and SOL instead |
| Every other state | Available | On automatically; you can opt out |
Coinbase’s column follows its staking eligibility page, and existing stakers in the four blocked states can still unstake at any time. Gemini’s rows follow its Asset Rewards FAQ, which gives the commission as 35% in one answer and 30% in another. The table uses the ceiling in its Asset Rewards fee schedule of October 7, 2026, so plan on that.
Your coins aren’t locked in Asset Rewards, and Gemini aims to stake about half of the enrolled pool while keeping the rest for withdrawals. If withdrawals ever outrun that reserve, its program terms let it queue them.
Gemini Staking works differently. It opened to New York customers on February 10, 2026, for ETH and SOL, and its own fee schedule has the same ceiling. Getting out takes time: ETH unbonding runs 6 to 60 days and SOL about 3 to 4, and you can’t sell or withdraw those coins while you wait. A coin can’t earn in both Gemini programs at once.
Coinbase staking has a wait too. A staked balance can’t be sold or sent until you unstake it, and unstaking takes from a few hours to a few weeks, depending on the asset. On both platforms, slashing, a network penalty on a validator, can shrink staked coins, and whether the company replaces them depends on the cause.
Watch the automatic enrollment. In most states, an ETH or SOL balance on Gemini starts earning rewards unless you turn Asset Rewards off in Account Settings. Staking rewards earned through an exchange are income in the year you receive them, under IRS Revenue Ruling 2023-14, and Gemini reports staking income on Form 1099-MISC. So a balance you never meant to stake can still add income to your return.
Security and legal record
Coinbase disclosed in May 2025 that an attacker had apparently paid support contractors and employees outside the US to pull customer data, including government ID images, balances and transaction history. The company’s Form 8-K states that no passwords or private keys were compromised, and that it intended to reimburse eligible retail customers who sent funds to the attacker because of it. It preliminarily estimated the cost at about $180 million to $400 million.
That stolen data is one reason a scam caller may know your balance. The SEC’s lawsuit against Coinbase is over: the SEC dismissed the case on February 27, 2025, a decision it tied to policy rather than to the merits.
Gemini’s record centers on Earn, a program that let customers lend their crypto to Genesis Global Capital. When Genesis melted down, Earn customers couldn’t reach their assets. In February 2024 Gemini committed to the New York regulator to return at least $1.1 billion to Earn customers through the Genesis bankruptcy, put $40 million into it and pay a $37 million fine.
On January 23, 2026, the SEC filed to drop its Earn lawsuit against Gemini, with prejudice. It cited the 100 percent in-kind return of Earn investors’ crypto.
Moving crypto between Coinbase and Gemini
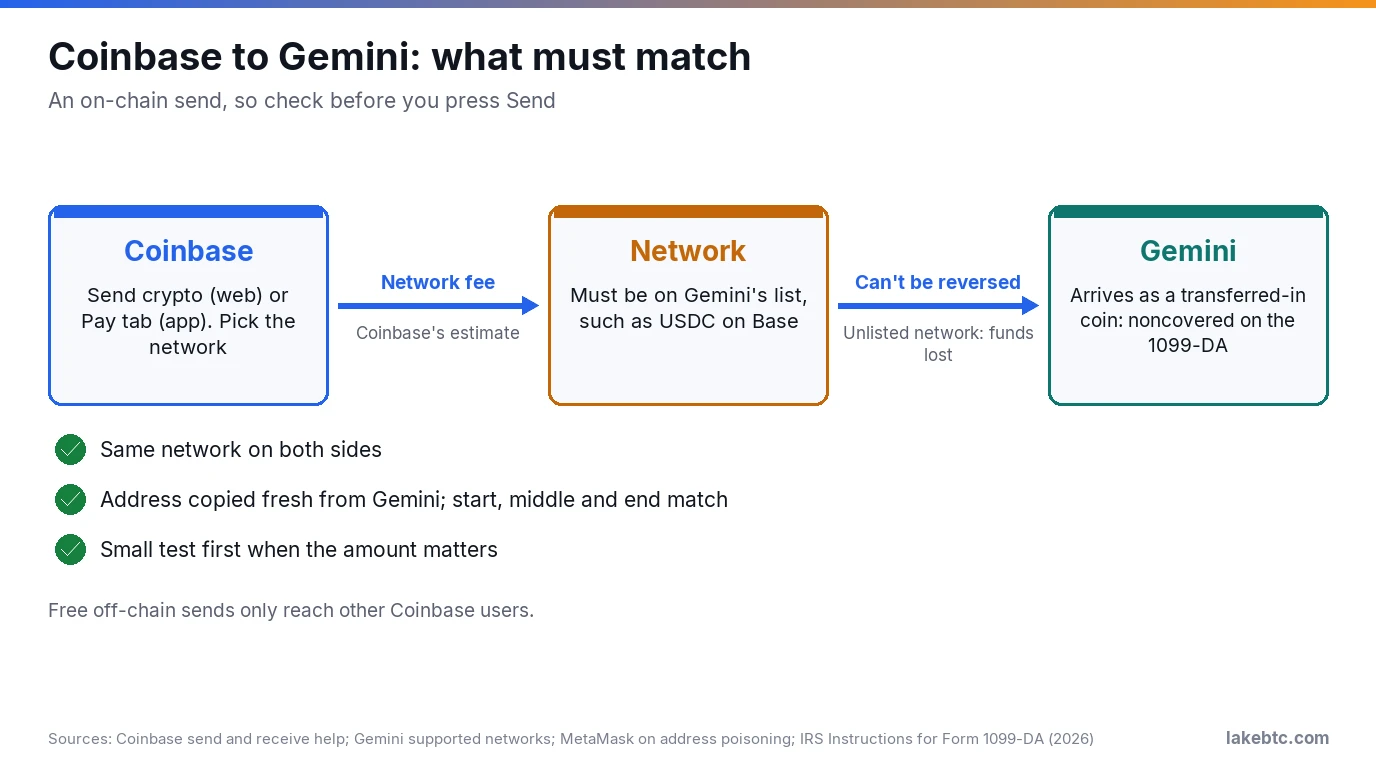
A transfer between the two is an on-chain send. It can’t be reversed, and the network you pick when sending has to be one the receiving side accepts.
- Check the coin and the network on the receiving side first. Gemini’s network list takes USDC on Ethereum, Base, Arbitrum, Optimism, Polygon, Solana, Avalanche and Worldchain, and ETH on Ethereum, Arbitrum, Optimism and Base. A token sent to Gemini on a network that isn’t listed is lost.
- On Coinbase, choose Send crypto on the web or the Pay tab in the app. Pick the asset and amount, then pick the network that matches step 1.
- Copy the deposit address fresh from Gemini’s deposit screen for that coin and network, never from your transaction history, and paste it into Coinbase. Check characters at the start, the middle and the end against what Gemini shows. In an address poisoning scam, someone sends you a tiny transfer from a look-alike address that matches only the start and end, so it sits in your history ready to be copied by mistake.
- Review the details (Preview Send on the web) and read the network fee. Coinbase charges its estimate of the network fee, and USDT also gets a 0.01% processing fee, capped at 20 USDT.
- When the amount matters, send a small test first and wait until it arrives. Then send the rest to the same address on the same network.
Going the other way, Gemini charges a dynamic withdrawal fee meant to match the network fee, and it doesn’t keep that fee. For ERC-20 tokens you pay the gas in the token you’re withdrawing. USDT isn’t available to Gemini clients in New York.
Sending to a wallet you control works the same way, with one extra job first: write down the wallet’s seed phrase (or set up its other recovery method) before any coins land in it. For a hardware wallet, follow the Coinbase to cold wallet steps.
Support, and the scam that copies it
Gemini doesn’t offer phone support, and its security page says genuine Gemini emails end in .gemini.com. It does send a one-time SMS code to verify your phone number, and its Credit Card support team may call you about your card. But its guide to genuine messages says it won’t cold-call you about support or account management. So an unexpected call from “Gemini support” about your account isn’t Gemini.
Coinbase does run phone support, which gives scammers a script to copy. Its agents won’t ask you to move funds, hand you a seed phrase, request your password or 2FA code, or ask you to install software. If a real call drops, the agent calls back within five minutes and re-verifies you with a security question. A caller who asks for any of those things is running a support impersonation scam, and the same tricks show up in fake Coinbase emails.
This is where people actually lose money. Crypto complaints to the FBI’s IC3 for 2025 reported $11.366 billion in losses, and fake tech and customer support accounted for $1.226 billion of that, second only to investment fraud.
Hang up, open the app yourself, and turn on withdrawal allowlisting so coins can only leave to addresses you’ve approved. Both require 2FA to get into your account. Gemini also requires it for withdrawals by default, while Coinbase asks for it on certain higher-value sends but not routine ones. Coinbase rates a pair of hardware security keys as its highest-security 2FA option and text messages as the least secure.
Tax forms you’ll get from each
Both send Form 1099-DA, on the same IRS schedule. The return you’ll file next spring covers 2026 sales, so the second row is the one that applies now.
| Tax year or item | What you get |
|---|---|
| 2025 sales (filed in 2026) | 1099-DA with gross proceeds only, no cost basis |
| 2026 sales (filed in 2027) | 1099-DA with gross proceeds, plus cost basis for covered assets: bought after 2025 in that account and held there until sold |
| Coins you transferred in | Noncovered: the broker doesn’t have to report their basis, whatever year you bought them |
| Gemini staking, referral and stablecoin rewards | Form 1099-MISC, not the 1099-DA |
Coinbase’s 2025 forms were due by March 17, 2026, and Gemini sends statements by February 15 each year. Moving coins between the two has a tax side effect. The 1099-DA instructions make a coin transferred in to a broker a noncovered security, so the receiving exchange doesn’t have to report your basis to the IRS. Keep your purchase records from the sending side. Gemini can show gain or loss on your copy only if you enter the cost and date yourself.
Coinbase doesn’t report the send itself on the form, only the crypto sold or used to pay the network fee. And since January 1, 2025, IRS basis rules apply wallet by wallet and account by account, so each exchange’s records stand on their own. Gross proceeds aren’t your gain, and a tax professional can confirm how this applies to you.
Frequently Asked Questions
Is my crypto safe on Gemini?
Gemini’s user agreement holds your crypto as yours, 2FA is on by default and you can restrict withdrawals to approved addresses. The risks are the ones any custodian carries: insurance covers a small share, and neither its crypto insurance nor FDIC pass-through on your cash covers losses from someone getting into your account.
Is Gemini crypto exchange in trouble?
Its Earn case is closed: Earn investors got 100 percent of their crypto back in kind, and the SEC dismissed its case in January 2026. The business is still losing money: a $582.8 million net loss in 2025 and $216.7 million in the first half of 2026. In February 2026 it approved a plan to leave the UK, the EU and other European countries, and Australia, cutting up to about 25% of its staff, while US and Singapore operations continue. Listed on the Nasdaq as GEMI since September 12, 2025, it files quarterly reports you can check.
Is Gemini good for crypto trading?
ActiveTrader is a full order book with published tiers, and the RLUSD/USD, USDC/GUSD and GUSD/USD pairs trade at 0.00% fees. Rates drop to 0.400% maker and 0.800% taker at the second tier, so your volume or balance matters.
Which costs less: Coinbase or Gemini?
It depends on the screen. You can price Gemini’s order book today from its public schedule, but Coinbase’s Advanced rate needs a sign-in. For simple buys, compare each preview total for the same amount and payment method.
Gemini Credit Card or Coinbase One Card?
The Gemini Credit Card, issued by WebBank, has no annual fee and pays up to 4% back in crypto, with the 4% rate limited to $300 of spend a month. The Coinbase One Card pays up to 4% in bitcoin but needs a Coinbase One membership, and Basic members qualify only on an annual plan.
Can I send crypto from Coinbase to Gemini for free?
No. It’s an on-chain send with a network fee. Free off-chain sends only reach another Coinbase user by email, phone number or username.
What to do next
If staking is your main reason, find your state in the staking table before you deposit. If it’s trading, price your usual order on Gemini’s public schedule and on Coinbase’s Advanced fees page once you’re signed in.
Fund it by bank transfer, add a hardware security key for 2FA and switch on withdrawal allowlisting. On Gemini, decide whether you want Asset Rewards on or off. Move coins you won’t trade to a wallet you control, using the transfer steps above, and plan for a wait after a bank deposit. Gemini holds withdrawals until an ACH transfer clears, typically four to five business days, and Coinbase lets you send purchased crypto once the funds settle, which usually takes up to five business days.
Drafted with AI by the LakeBTC Editorial Team, then edited and fact-checked against the sources linked in the text. How we use AI · Report an error
Update history 1
- Rewritten and re-checked against primary sources.